
Dr Nazem Khan
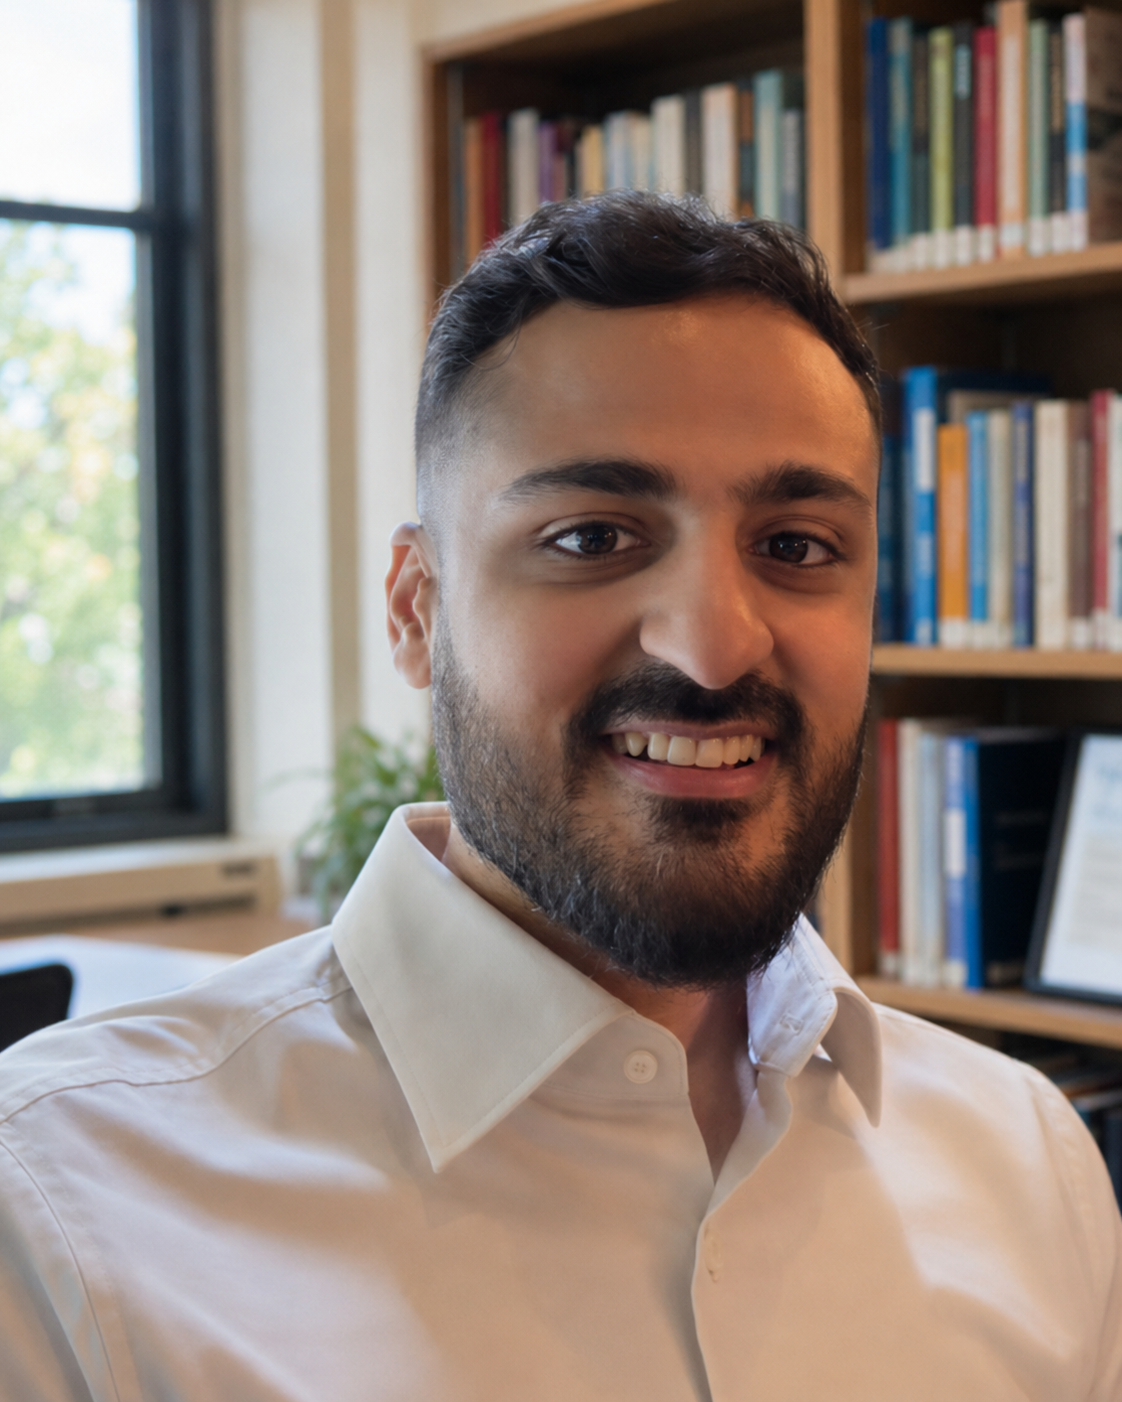
About
I am an Assistant Professor in the Department of Statistics at the University of Warwick. My research lies in mathematical finance, with strong links to risk management, decentralised finance and network theory.
Before returning to Warwick in September 2026, I was a Departmental Lecturer at Oxford and a postdoctoral researcher at Dublin City University with Paolo Guasoni. I completed my PhD at Warwick, supervised by Vicky Henderson and Martin Herdegen.
Contact and links
Email: nazem.khan.1@warwick.ac.uk
Office: 3.12, Mathematical Sciences Building
Office hours: To be confirmed
Academic links
Intercalated Years
In the academic year 2026–27, I am the Intercalated Year Coordinator for the Department of Statistics.Current Warwick Statistics students who are interested in undertaking a year in industry or studying abroad during the 2027–28 academic year are welcome to contact me.
Further information is available in the Intercalated Year Handbook and from the University’s Student Mobility team.Link opens in a new window
Teaching
In the academic year 2026–27 I will be:
- Tutorial leader for ST401: Stochastic Methods in FinanceLink opens in a new window
- Module leader for ST958: Advanced Trading StrategiesLink opens in a new window
- Delivering a lecture for ST921: Statistical FrontiersLink opens in a new window
Research
Much of my research asks how financial decisions and financial systems can be made robust to adverse outcomes. My work is organised around two principal strands.
Risk, utility and portfolio choice
I study how risk measures and utility functionals shape portfolio choice, arbitrage and pricing. A recurring question is whether a financial criterion responds adequately to the accumulation of large losses, and how this determines the existence, robustness and economic meaning of optimisation problems.
Decentralised finance and resilient networks
I study the design of financial infrastructure when payments, links and failures are costly. This includes payment-channel optimisation and the construction of decentralised networks that balance short routes and strong connectivity against maintenance costs and the concentration of activity at a small number of hubs.
Papers
Publications
- Risk, utility and sensitivity to large lossesLink opens in a new window (with Martin Herdegen and Cosimo Munari) Mathematical Finance (Forthcoming)
- ρ-arbitrage and ρ-consistent pricing for star-shaped risk measuresLink opens in a new window (with Martin Herdegen) Mathematics of Operations Research (2025)
- Mean-ρ portfolio selection and ρ-arbitrage for coherent risk measuresLink opens in a new window (with Martin Herdegen) Mathematical Finance (2022)
Preprints
- Chain or channel? Channel optimization with heterogeneous paymentsLink opens in a new window (with Paolo Guasoni)
- How to reduce risk by increasing riskLink opens in a new window (with Martin Herdegen and Cosimo Munari)
- The interplay between utility and risk in portfolio selectionLink opens in a new window (with Leonardo Baggiani and Martin Herdegen)